For more stories like this, sign up for the PLANADVISERdash daily newsletter.
In Practice November 16, 2026
Employers Say Emergency Savings Programs Strengthen Workers’ Retirement Readiness
Starbucks’ program, providing access to liquid savings, has attracted roughly 16,000 participants and generated more than $20 million in savings.
Reported by
Valentina Baez
Starbucks Coffee Co. implemented an emergency savings program after employee surveys revealed workers wanted greater access to liquid savings for unexpected expenses.
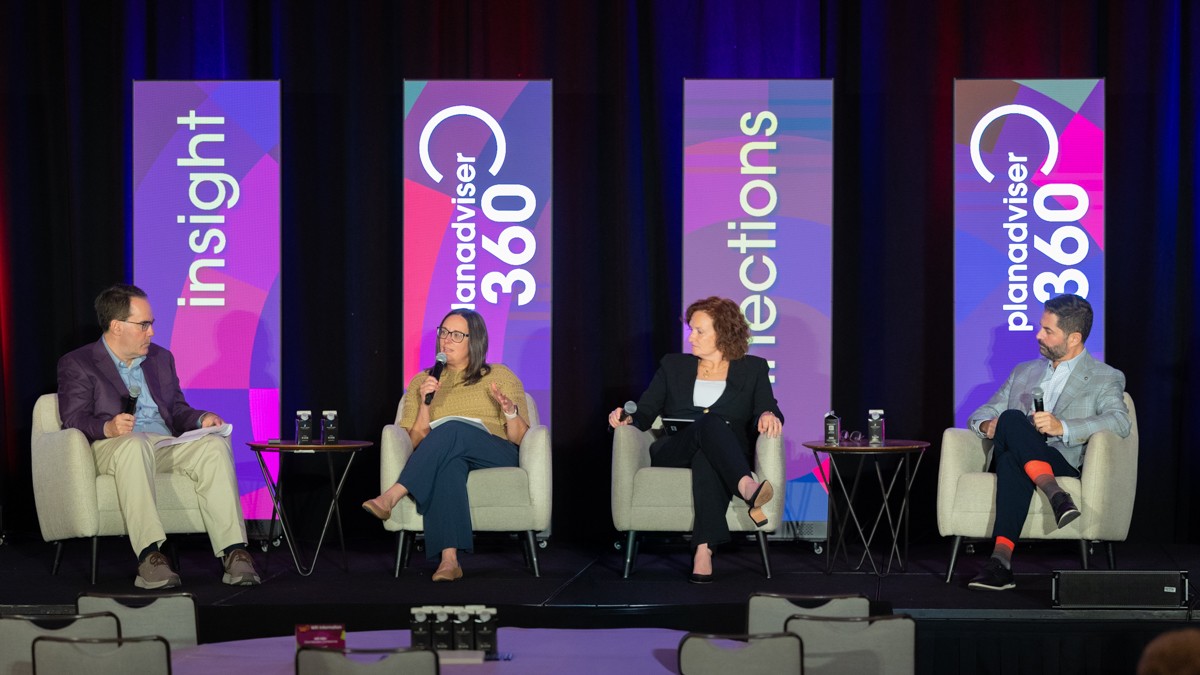
During the November 9 panel discussion “From Benefit to Bedrock: What Emergency Savings Means for Your Practice,” at the 2026 PLANADVISER 360 Conference in Orlando, Florida, representatives from Starbucks, T. Rowe Price and Marsh McLennan Agency said emergency savings programs are increasingly becoming a critical component of workplace financial wellness efforts. The programs’ goal: to help employees manage short-term financial shocks while supporting long-term retirement goals.
According to Christen Davis, benefits director of savings, retirement and recognition at Starbucks, the company regularly surveys employees. Their feedback, combined with research showing that many Americans lack even a few hundred dollars to cover an unexpected expense, convinced company leaders there was a need to enhance Starbucks’ financial benefit offerings.
“We were hearing from them that they felt there was a gap in having a liquid short-term savings vehicle they could use to help prepare for their future,” Davis said.
A Missing Piece in Benefits
Starbucks already offered a range of financial benefits, including a 401(k) plan, company stock grants, and tuition coverage through Arizona State University, but the company ultimately viewed emergency savings as a missing piece in a broader financial wellness strategy. “We saw that emergency savings would be a good complement to add to that portfolio of benefits—to help people be prepared at all [points] of their career,” she told the audience.
Starbucks’ emergency savings program launched in 2022. Alerting all 200,000 employees was a separate issue. Davis said communication remains one of the biggest challenges for Starbucks, whose U.S. workforce is spread across more than 16,500 coffee shops, not to mention roasting and manufacturing facilities, distribution and supply-chain operations and corporate offices.
To promote the program, the company used a multichannel campaign that included email, internal social-media channels, a dedicated microsite developed with Fidelity Investments, Starbucks’ own internal benefits hub, in-store flyers and conversations led by store managers. Despite noting an initial surge of roughly 11,000 enrollments in the first three months after launch, the sponsor has found it hard to maintain awareness among its retail employees.
The company thus enlisted coffeehouse leaders to discuss the program directly with their staff, and Davis said sustaining engagement among those employees, who are not regularly at a computer, remains an ongoing challenge.
She shared that the company’s program has attracted around 16,000 participants and generated more than $20 million in savings since it launched.
‘Gateway’ to Retirement Savings
Other panelists, commenting on the programs in general, argued that emergency savings should not be viewed as separate from retirement preparedness, but as a key driver of it.
Nick Maynard, senior vice president at Commonwealth, shared research from the BlackRock Emergency Savings Initiative, which showed that workers are more likely to participate in retirement plans and less likely to tap their accounts when they have access to short-term savings.
“Emergency savings [are] crucial to retirement security,” Maynard said. Later in the discussion, he described emergency savings as “almost like a gateway to retirement security.”
Anthony Carter, director of financial wellness at Compass Financial Partners, a Division of Marsh McLennan Agency LLC, recommended that adviser attendees ask their clients a direct question about allowing for emergency saving: “Why haven’t we already started doing this?”
Panelist Rachel Weker, a retirement strategist at T. Rowe Price, said her firm’s research has found a clear link between emergency savings and retirement-plan behavior. Drawing on data from 2.4 million participants, she said workers who lacked emergency savings saved less for retirement and were more likely to take hardship withdrawals and other distributions from their retirement accounts.
According to Weker, nearly half of participants surveyed said they would not have access to $1,000 to cover an emergency expense. Participants without emergency savings also saved for retirement at rates roughly 2 percentage points lower than those who had emergency reserves, she said.
Asked why workers are not saving more for retirement, Weker said, “The No. 1 reason people give is, ‘I just don’t have the capacity to do more than I am.’” Building emergency savings was among the most important financial priorities that respondents cited.
Weker said her firm’s findings also suggested that helping workers prepare for unexpected expenses reduced the need to borrow from or withdraw assets from workplace retirement plans.