Want the latest retirement plan adviser news and insights? Sign up for PLANADVISER newsletters.
In Practice November 9, 2026
Anne Lester Explains How Private Market Assets Fit Into 401(k) Plans
The self-described money mentor discussed the potential implementation of private market investments in DC plans and highlighted royalties as an emerging asset class, at the PLANADVISER 360 Conference.
Reported by
Valentina Baez
The notion of incorporating private market assets such as private equity and private credit into defined contribution plans is not new to retirement plan advisers.
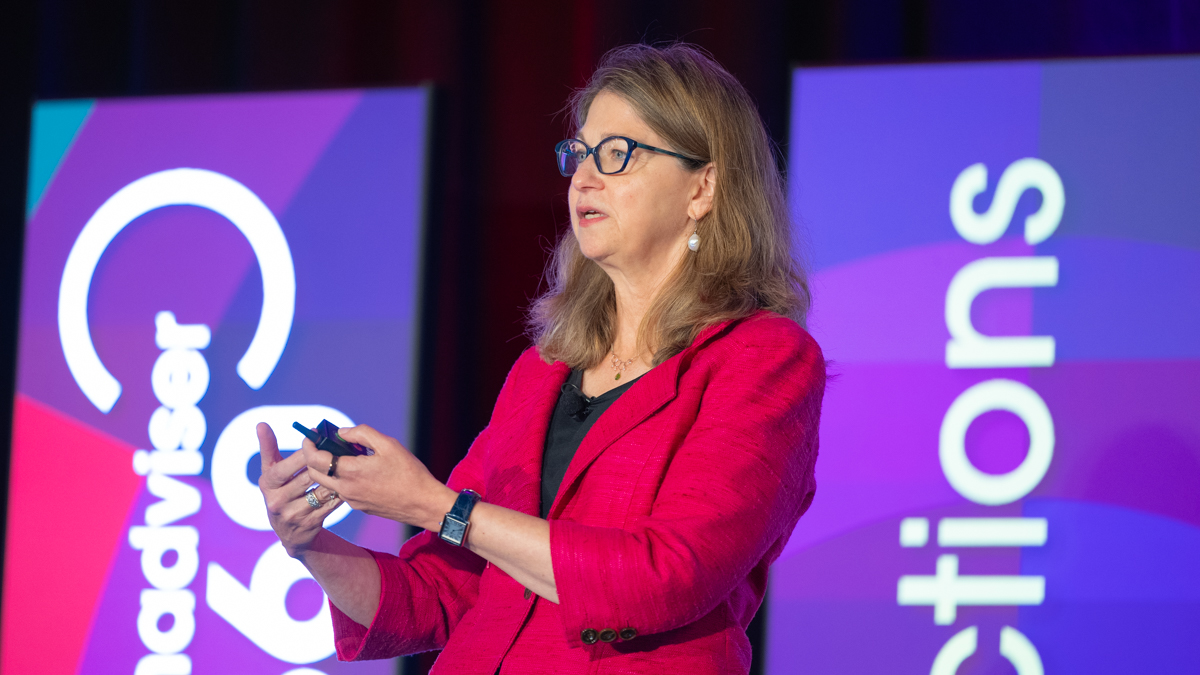
However, thoroughly understanding how the assets fit into a 401(k) plan and how the markets are evolving is a lesson that Anne Lester, a member of Partners Group’s board of directors, shared with audience members in Bringing Private Markets into 401(k) Plans, at the PLANADVISER 360 Conference in Orlando, Florida, on Monday.
According to Lester, the industry has arrived at a place of increased comfort with the idea of private markets for retirement investments, which leaves a question for plan advisers and plan sponsors to grapple with.
“The question now is: With more tools in the toolbox, more ways of accessing different asset classes, how can we contemplate whether or not it is the right thing to do for our plans?” she said to the audience.
New Tools in the Toolbox
Lester’s analogy of new tools in the toolbox segued into her description of the various types of private market assets now available for 401(k) plans.
These assets include private equity and private credit—which Lester highlighted as the ones most often featured in plans today—along with private infrastructure and private real estate. The newest asset Lester called out was royalties.
“Royalties … is [a class] the Partners Group has just started over the past few years, [two examples being] music catalogs [and] pharmaceuticals,” she said. “These income streams tend to be more inflation-sensitive, very predictable.”
While the range of private market investments continues to expand, Lester said, advisers should focus less on the novelty of the asset class and more on how it works within a retirement plan’s existing investment structure.
Because of those considerations, private market investments generally should be incorporated within professionally managed retirement solutions.
“This belongs inside a [qualified default investment alternative],” she said, pointing to target-date funds and managed accounts as the most practical vehicles for incorporating private market exposure.
While the expanding menu of private market assets may offer additional sources of return and diversification, Lester also said, advisers and plan sponsors must additionally consider practical issues such as liquidity, valuation and portfolio construction when evaluating an investment’s suitability for the retirement plan.
In a TDF, liquidity concerns are generally managed at the fund level because private market allocations represent only a portion of a broadly diversified portfolio that remains largely invested in liquid assets.
“When you think about the risks of one component of your target-date fund not having liquidity if something happens, you have the rest of that pool of assets to meet participant cash flows,” Lester said.
Managed accounts, by contrast, may require more careful consideration of how individual participant portfolios access private market investments and liquidity.
What Providers and Sponsors Should Know
While private market allocations are drawing increased attention from plan sponsors, implementation matters as much as the asset class itself, Lester argued.
For advisers evaluating private market solutions, operational due diligence should be a primary focus, she said. Among the questions plan fiduciaries should ask are how assets are valued, how liquidity is managed, and whether a manager has sufficient scale and diversification across private market strategies.
“It is true that the private markets are not immune from economic ‘scenarios,’” Lester said.
However, liquidity remains one of the most important considerations because private assets cannot always be sold as quickly as publicly traded securities.
“There is relatively limited liquidity available, and it is absolutely something you need to talk to your provider about,” Lester said. “You have to have a robust process for how you’re going to manage that situation.”
She noted that plan sponsors should know how a provider would respond during periods when redemption requests exceed available liquidity, including what mechanisms are available to meet participant needs and how the provider would communicate about these and the processes it would follow.
Beyond operational concerns, advisers should also evaluate what role a private market allocation is intended to play within a portfolio.
According to Lester, private equity and private credit have attracted the greatest interest from DC plans because they can serve as substitutes for traditional equity and fixed-income exposure while potentially improving long-term risk-adjusted returns.
When assessing managers, she said, advisers should look for firms with demonstrated private market experience, daily valuation capabilities, periodic liquidity programs and transparent allocation processes.
“You want a fair and transparent allocation process,” Lester said. “You want to be working with partners where all of your clients have access to those investment opportunities.”
« Terminated Employees’ Severance Claims Can Proceed, per Illinois District Court